Can Americans Buy Property in Spain? The Rules in 2026

The short answer to can Americans buy property in Spain is yes, and on exactly the same terms as a Spanish citizen. There is no quota, no minimum price, no requirement to live here and no approval process for ordinary residential property. A US citizen buying an apartment on the Costa del Sol goes through the same notary, pays the same taxes and receives the same title as a buyer from Madrid.
The longer answer has three parts worth knowing. There is one narrow legal exception, which applies only in designated defence zones. There is a much-discussed proposal for a 100% tax on some foreign buyers, which is real but has not become law. And there is a US reporting rule that is simpler than many people expect. We moved to Estepona from Germany ourselves, so we know from the inside what it is to buy as a foreigner here, and I look after every buyer personally. This guide covers the buying side; if you are moving as well, our guide to moving to Spain from the USA covers visas and residence.
Can Americans buy property in Spain? Yes, with the same rights as Spaniards
Put the question "can Americans buy property in Spain?" to a Spanish lawyer and the law gives a plain answer: Spanish property law makes no distinction by nationality for ordinary residential purchases. An American can buy a resale apartment, a new build, a villa or a plot, hold it in their own name, let it, leave it to their children and sell it, all on the same legal footing as anyone else. Title is recorded in the Land Registry in the same way, and the same protections apply.
What differs is administrative rather than legal. As a foreigner you need a foreign identity number, the NIE, before you can sign at the notary. You need a Spanish bank account for the payments that follow. And as someone living outside the European Union you pay Spanish tax on the property at non-resident rates, which are higher than the EU rates for some income. None of this is a barrier; it is paperwork, and it is the same paperwork a British, Norwegian or Canadian buyer faces.
You also do not need to be in Spain to buy. With a power of attorney granted to a Spanish lawyer, a purchase can be completed from start to finish without you at the notary. Most buyers still come over for the viewing, and many sign the power of attorney here during that trip, because it is simpler than arranging one in the US with an apostille and a sworn translation.

The one legal exception: defence zones
Spain has a law from 1975 on zones of interest for national defence, Law 8/1975, and it contains the only real restriction on foreigners buying property. Under Article 18, in areas designated as zones of restricted access to property by foreigners, a foreign buyer needs military authorisation to acquire land or buildings, to take a mortgage in their favour, or to build.
Three details make this far less alarming than it sounds. First, it applies only to specific, designated zones, not to the country as a whole. Second, the law itself exempts areas declared of national tourist interest, where the authorisation is treated as already granted, subject to any conditions set in advance. Third, and most importantly for a buyer, Article 20 requires notaries and Land Registrars to demand the authorisation before they execute or register the deed. A property in such a zone cannot be sold to you by accident: the notary will not proceed without it.
The same law extends the requirement to Spanish companies in which non-EU owners hold more than half the capital or exercise decisive control, which matters if you were thinking of buying through a company. For an individual American buying a home, the practical step is simple: ask your lawyer to confirm whether the property sits in such a zone as part of the normal checks. We do not publish a list of affected locations, because the designations are specific and technical, and a lawyer checking the individual property is the right way to answer it.
The "100% tax" you may have read about
In January 2025 the Spanish government announced a tax of up to 100% on property purchases by certain foreign buyers, and the headline travelled fast in the US press. It is worth being precise about what exists and what does not.
What exists is a bill. On 27 May 2025 the Congress of Deputies admitted for consideration a bill from the governing Socialist group, Bill 122/000196, on promoting affordable rental housing. Among its measures is a proposed state tax on transfers of property to buyers not resident in the European Union, at a rate the text sets at cien por ciento, one hundred per cent, of the property's reference value, with the ordinary transfer tax deducted from it.
What does not exist is a law. At the time of writing, in September 2026, the bill has not been passed and no such tax is in force. A tax in Spain applies only once a law has been passed by Parliament and published in the Official State Gazette, and this one has done neither. Any purchase you make today is taxed under the rules described in this guide.
Note the criterion: the proposal is aimed at buyers resident outside the EU, not at buyers of a particular nationality. An American who lives in Spain would not be caught by it; a Spanish citizen living in New York, on its wording, would be. Legal commentators have raised serious doubts about whether a tax of that size could survive a constitutional challenge or be squared with EU rules on the free movement of capital. That debate is for lawyers. For a buyer, the fact that matters is that it is not law.
Why Americans who buy property in Spain look at Estepona
We work on the western Costa del Sol, from Sotogrande to Marbella, with Estepona at the centre, and the numbers explain a good part of the interest. On our own survey of 18 September 2026, new developments in the municipality of Estepona were asking €5,145 per square metre across 840 priced units in 118 schemes, against a resale index of €5,000 per square metre for August 2026. A new home costs only 2.9% more per square metre than an existing one, which is unusually narrow; our note on the new build premium in Estepona sets it out.
For a buyer from the US, where new construction and older stock often sit much further apart in price, that narrow gap changes the calculation. It makes new build, with its current standards, air conditioning designed in and a ten-year structural warranty, the obvious starting point rather than a premium choice. Long-term rents in Estepona averaged about €21 per square metre a month in August 2026, a gross yield of roughly 5.05%, which matters if you plan to let the home while you are not here.
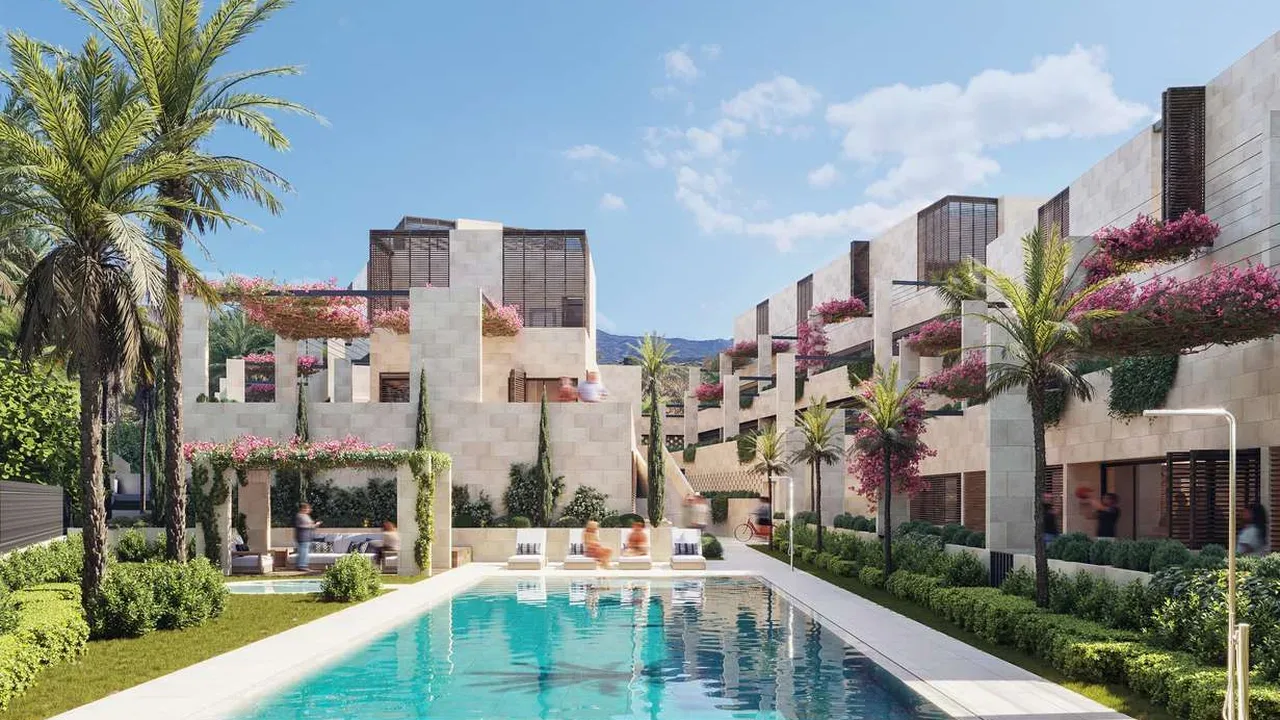
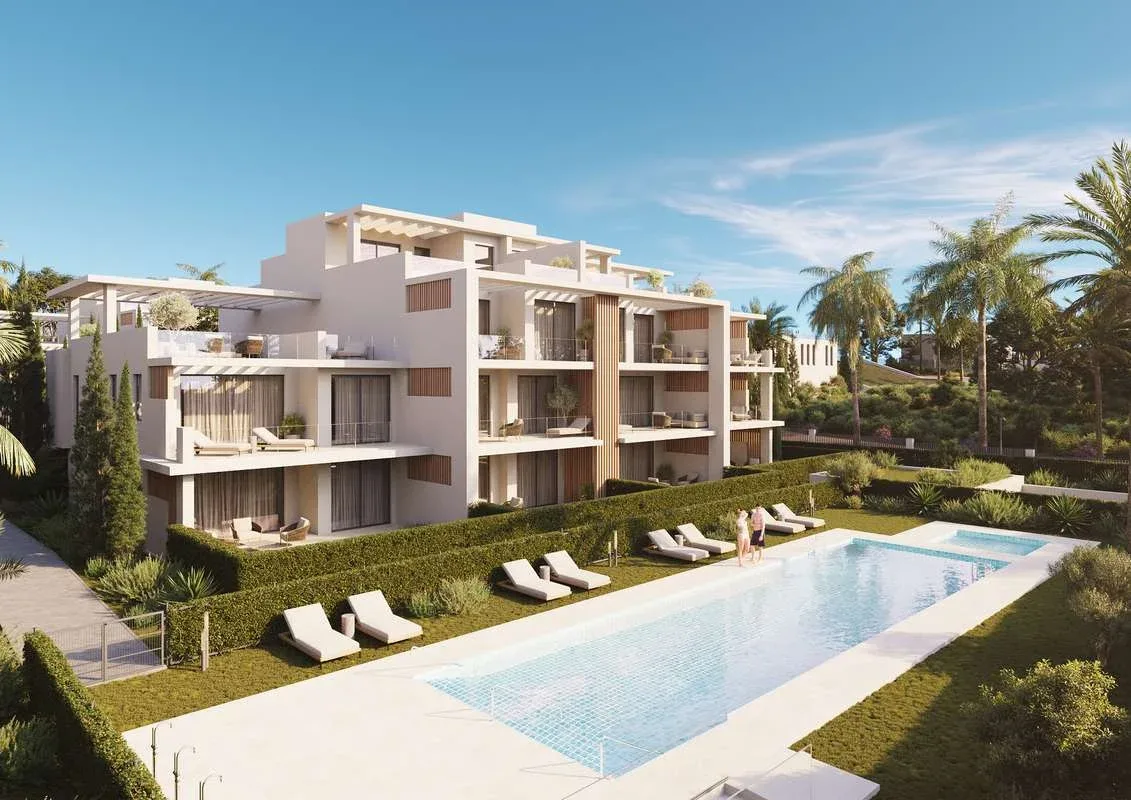
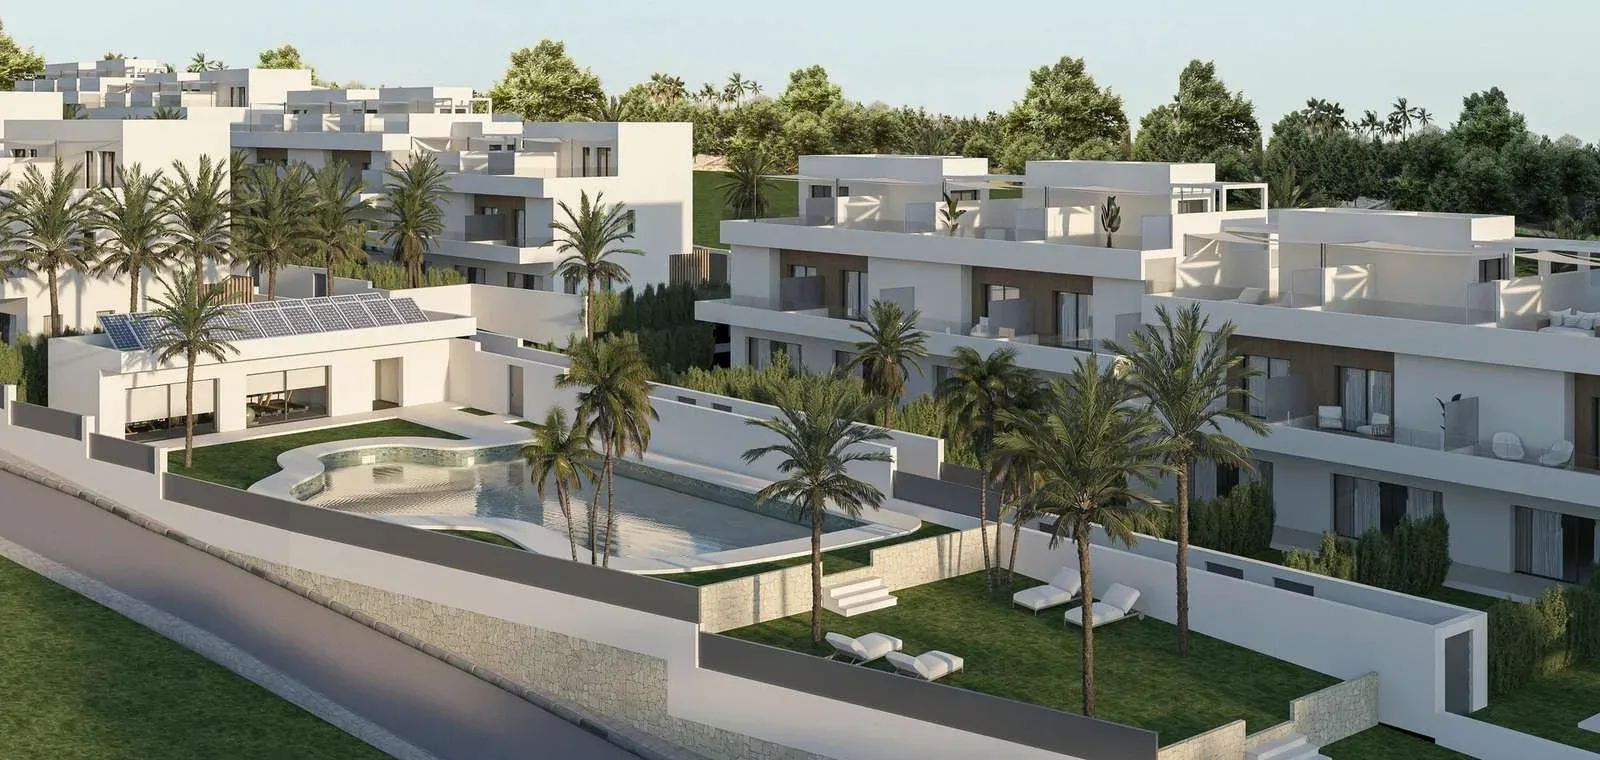
The town itself does the rest. Estepona has almost 80,000 residents, a restored old town, and a coastline that works all year rather than only in summer. That year-round life is the reason the rental market is deep and the reason owners who buy for the long term tend to stay. The current developments in Estepona show what is actually available.

New developments in Estepona
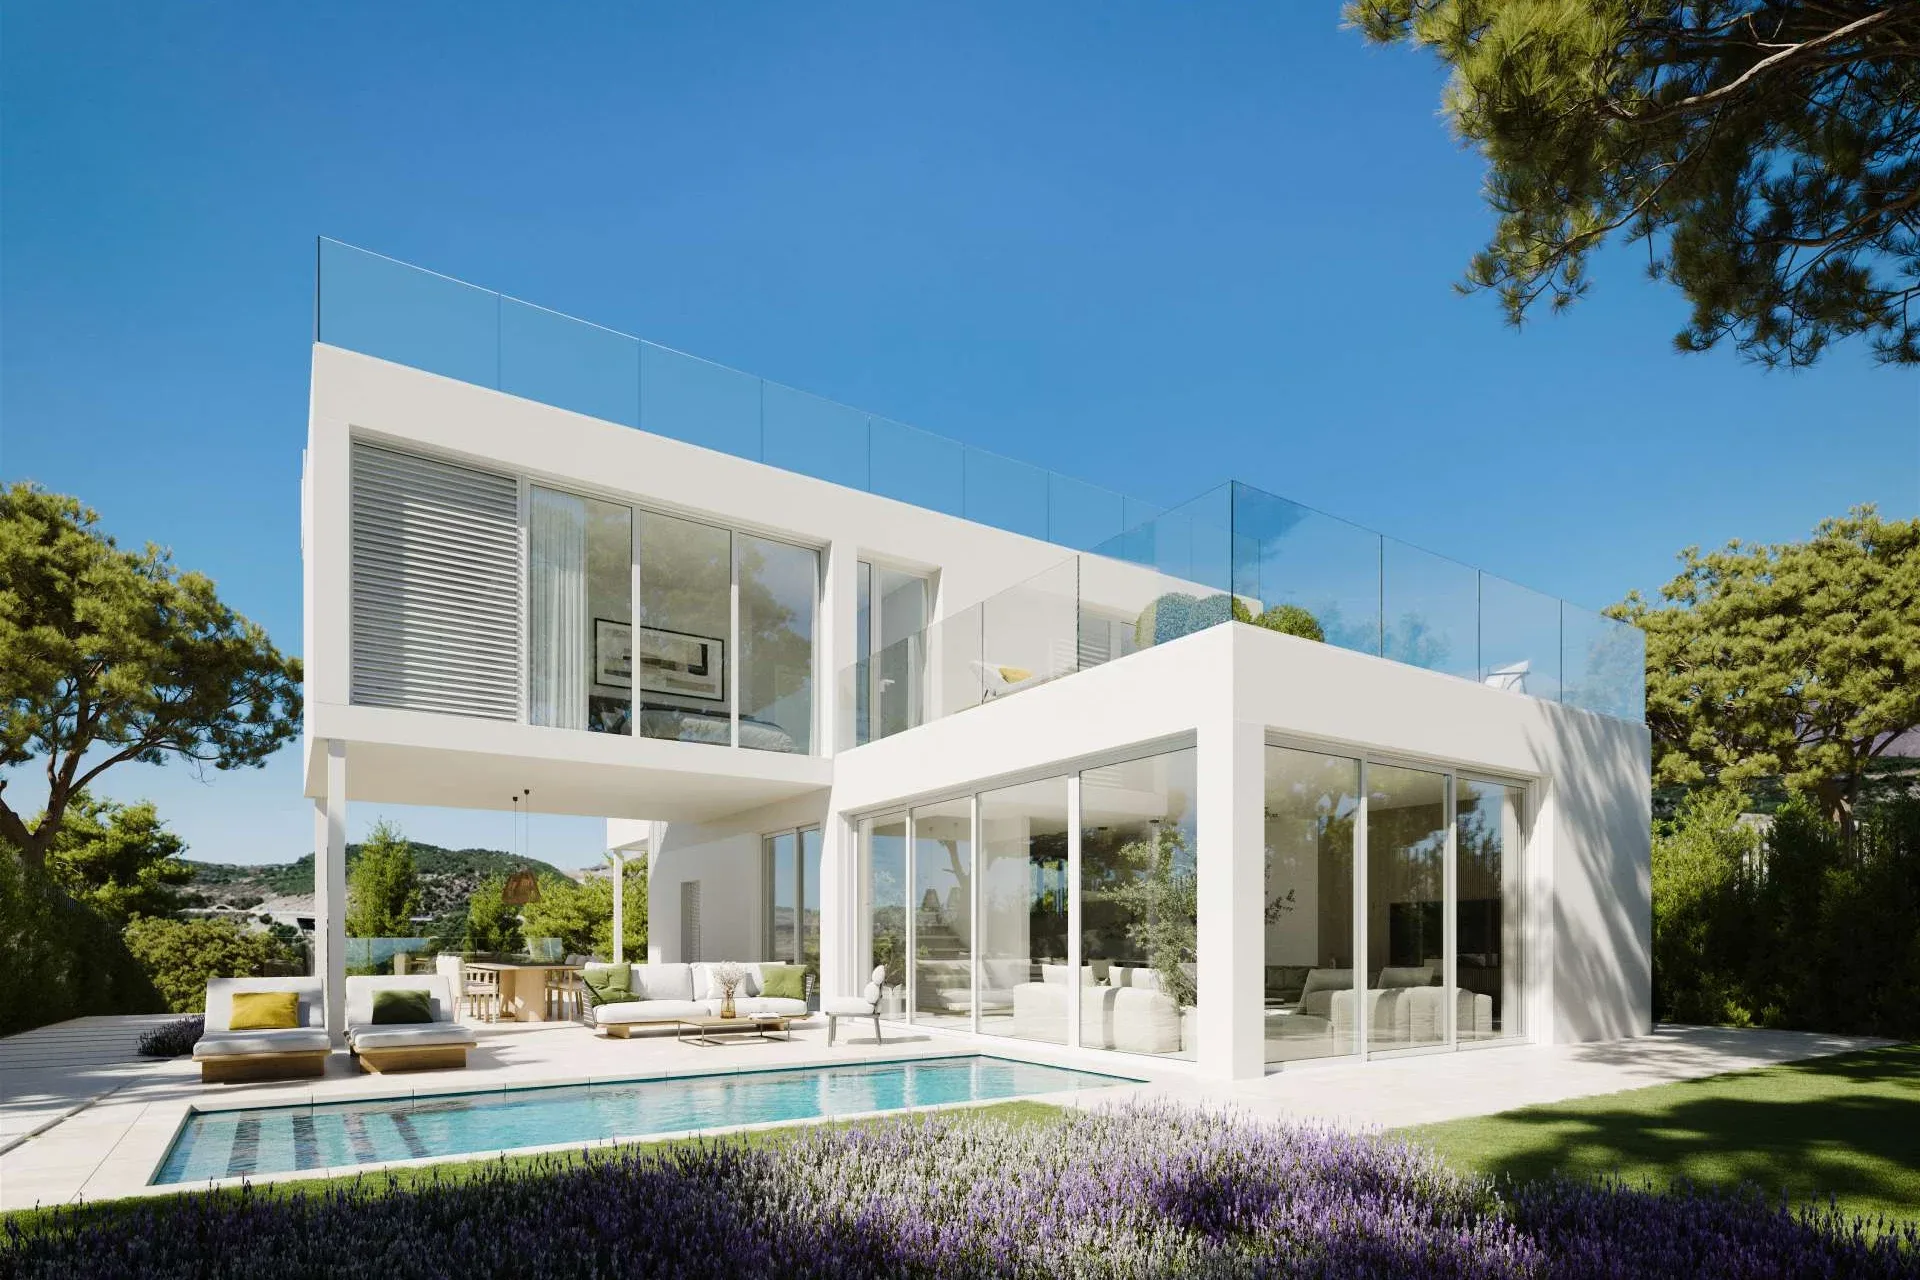
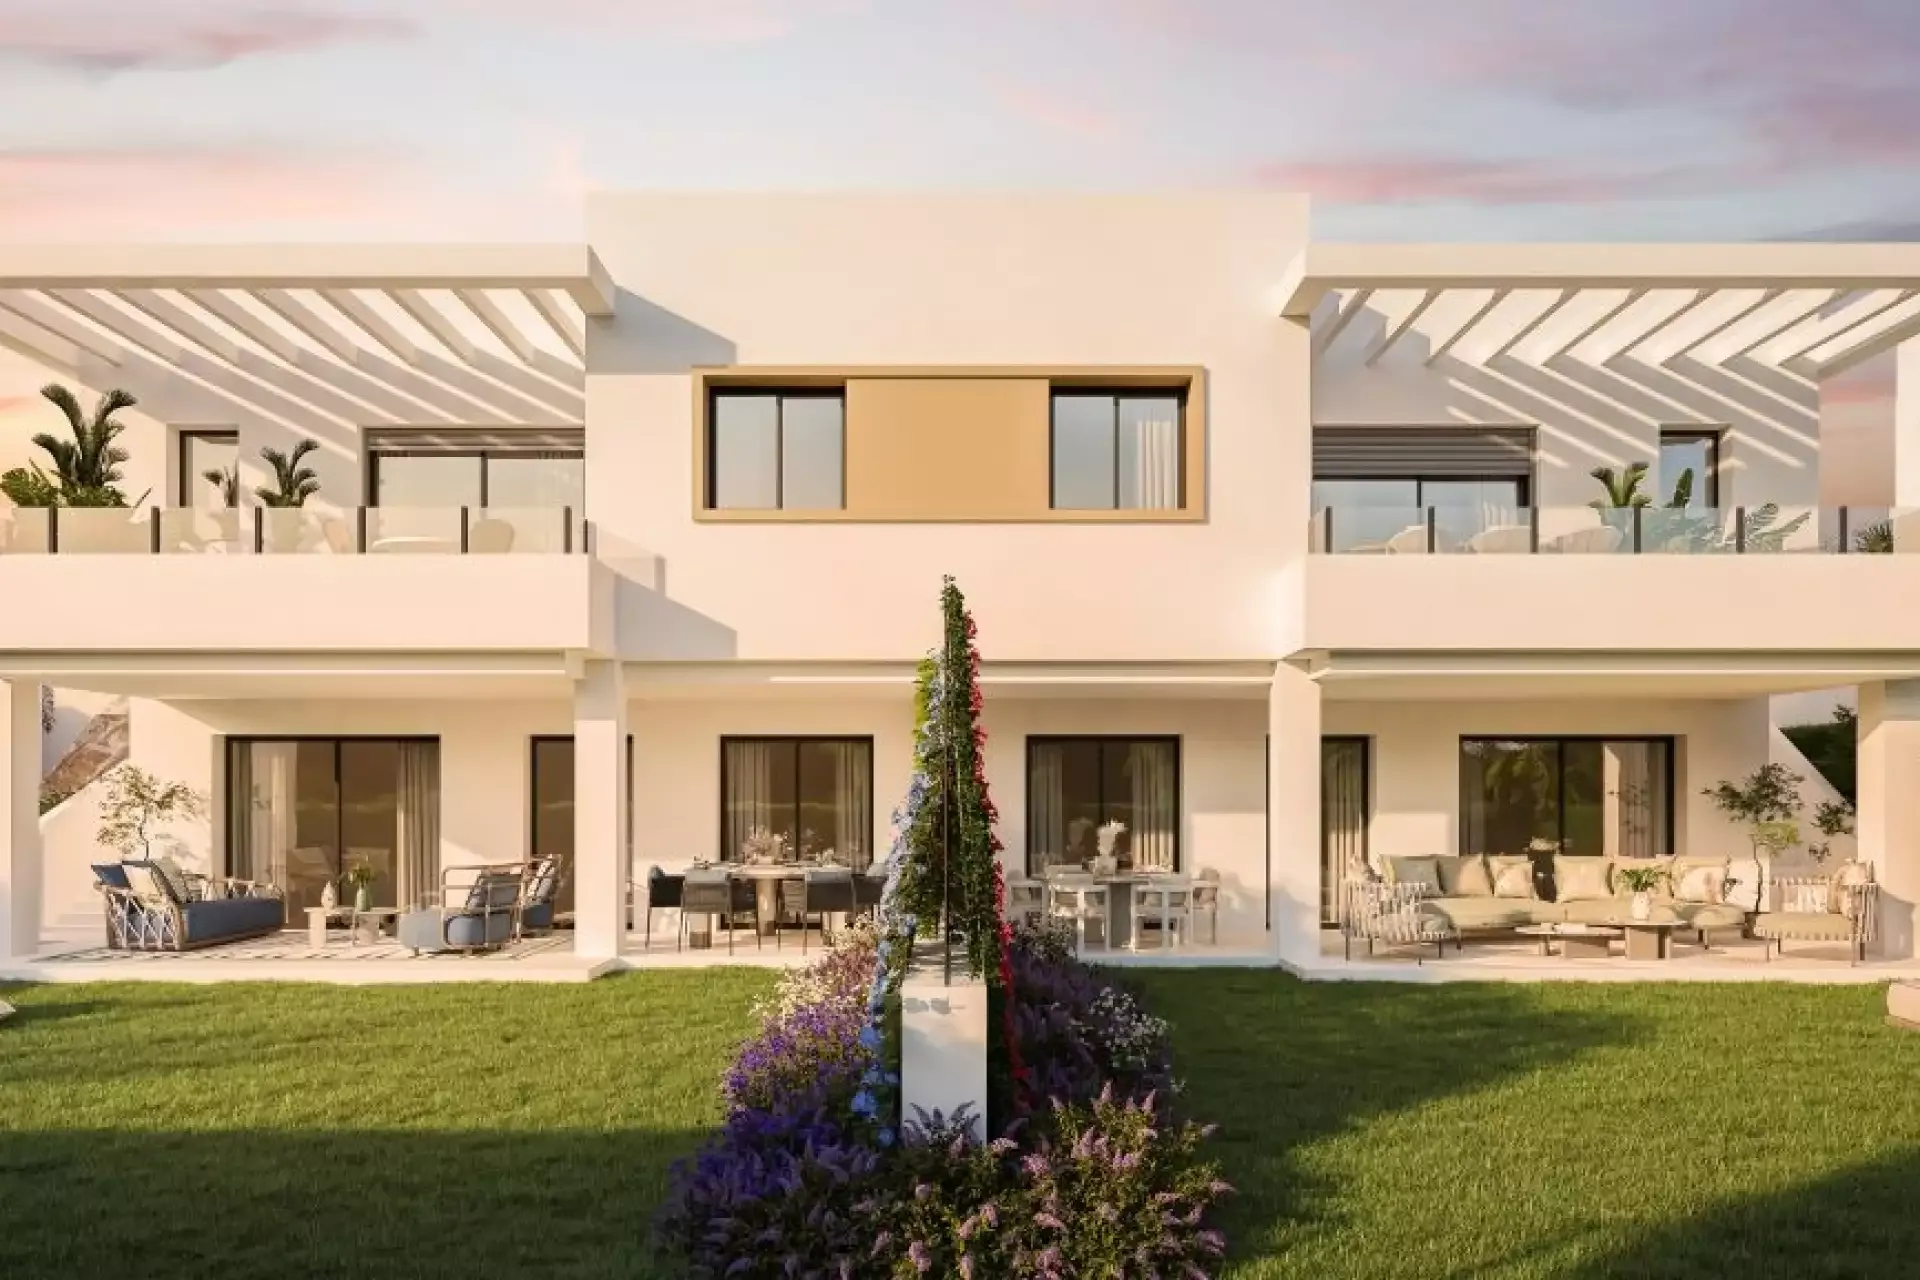
Buying is not moving: the 90-day rule and visas
This is the point most American buyers ask about first, so it deserves a clear answer. Buying property in Spain does not require a visa, and it does not give you one. Owning a home here changes nothing about how long you may stay.
As a US citizen you may spend up to 90 days in any 180-day period in the Schengen area without a visa, and that limit applies across all Schengen countries together, not per country. It applies to you whether or not you own a home in Spain. An American owner who wants to spend the winter here, say from November to March, is already past the limit, and needs a visa to do it lawfully.
Until April 2025, buying property worth €500,000 or more opened the golden visa route. That route has closed to new applications, and property on its own no longer leads to residence. The routes Americans now use are the non-lucrative visa, for those with passive income who will not work in Spain, and the digital nomad visa, for those who work remotely for employers or clients abroad. Our guides to moving to Spain from the USA and to alternatives to the golden visa cover both in detail.
What you need before you buy
Three things need to be in place before you can complete, and it pays to start all three the moment you reserve a property rather than waiting for the private contract.
- An NIE, the foreign identity number, which the notary requires for the deed
- A Spanish bank account, for the purchase payments, the taxes and the bills that follow
- An independent Spanish lawyer, acting only for you, with no link to the seller or the agent
- A power of attorney for that lawyer, if you will not be present at every step
- Funds in euros, or a plan for converting them, timed to the payment dates in your contract
The NIE can be applied for at a Spanish consulate in the US or in Spain, or through your lawyer with a power of attorney. Consulate appointment times vary widely between consular districts, so check yours early. Our guide to the NIE number in Spain sets out the three routes, the official fee and the five-day legal deadline that applies once your application is filed.
What to get done on your viewing trip
A viewing trip is usually the only time you are physically in Spain before completion, and a few hours of it can save weeks later. If you find a property and reserve it, use the remaining days for the tasks that are far easier in person.
Sign your power of attorney at a Spanish notary while you are here. A power of attorney signed in the US is perfectly valid, but it needs a notary there, an apostille under the Hague Convention and usually a sworn translation before a Spanish notary will accept it. Signed in Spain, it needs none of that, and your lawyer can start using it the same week.
Open the bank account in person if the bank allows it, since identity checks for non-residents are simpler face to face. If there is a free morning, book an NIE appointment at the local police station rather than waiting for a consulate slot at home. And meet your lawyer, even briefly: you will be trusting them with a six-figure transaction conducted largely by email, and it helps to have shaken hands once.
Finally, walk the neighbourhood at a time of day you would actually live in it, not only on the sunny afternoon of the viewing. "Can Americans buy property in Spain?" is never the real question on these trips; whether this street is the right one usually is.
The purchase, step by step
The Spanish process differs from an American closing in one important respect: there is no escrow agent and no title insurance culture. Instead, the public notary and the Land Registry do much of the work that title companies do in the US, and your own lawyer does the due diligence.
- Reservation. A deposit takes the property off the market while your lawyer carries out the checks.
- Due diligence. Your lawyer checks title and charges at the Land Registry, planning status, community debts and, where relevant, defence zone status.
- Private purchase contract. Usually with a further payment. On a new build this is also where the developer's bank guarantee must be handed to you.
- Completion at the notary. The public deed is signed, the balance is paid and the property becomes yours.
- Taxes and registration. Purchase taxes are paid and the deed is registered in your name at the Land Registry.
If you buy a new development off-plan, the sequence stretches over the construction period, with stage payments protected by a bank guarantee that Spanish law requires once the building licence is granted. Our guide to buying off-plan in Spain explains how that protection works, including a two-year deadline that can void the guarantee if a late project is left to drift.
What it costs to buy
Nationality makes no difference to the taxes on a purchase. What matters is whether the property is new or a resale, and which region it is in. In Andalusia the rates are as follows.
| Type of purchase | Tax | Rate in Andalusia |
|---|---|---|
| Resale | Transfer tax, ITP | 7% |
| New build | VAT, IVA | 10% |
| New build | Stamp duty, AJD | 1.2% |
On top of the tax come the notary and Land Registry fees for the deed of sale, your lawyer's fee and, if you borrow, the valuation. Taken together, a sensible budget is roughly 10 to 13% of the price on top of the price itself. On a new build the tax line is about four percentage points higher than on a resale, which is worth knowing because in Estepona the price gap between the two is so small that the tax difference can be the larger of the two.
Financing from the US
Can Americans buy property in Spain with a mortgage? Yes, Americans can borrow from Spanish banks as non-residents. Banks typically lend a smaller share of the price to buyers living abroad than to residents, and look closely at income earned in dollars, but the loan is governed by the same 2019 Mortgage Credit Act that protects every borrower. Among other things, that law puts most of the costs of setting up the mortgage on the bank, requires a binding offer ten days before signing, and caps early repayment fees. Our guide to the Spanish mortgage for non-residents covers all of it.
Paying for it: currency and transfers
A good currency plan protects the price you agreed. A purchase in euros funded from dollars moves with the exchange rate between agreeing the price and paying it, so it pays to plan the transfers.
The practical answers are simple. Transfer in planned tranches timed to the payment dates in your contract rather than all at once on the last day. Compare the rate your US bank offers with that of a specialist currency provider, because the spread between them on a six-figure transfer is real money. And keep the documentation for every transfer: the Spanish notary records how the price was paid, and the bank statements are your evidence for everything that follows, from the purchase deed to a future sale.
Moving large sums also brings your Spanish account into US reporting, which is the subject two sections down.
Spanish taxes as a US owner
Once you own, Spain taxes the property every year, and as a US resident you are taxed as a non-resident. The main lines are set out in our guide to non-resident property tax in Spain; here is what matters specifically for an American.
If you do not let the property
You pay IBI, the municipal property tax, to the town hall, and an annual non-resident income tax on a notional imputed income, filed on Modelo 210. The imputed income is 2% of the cadastral value, or 1.1% in municipalities with a recent general revaluation, and a US resident pays 24% on that figure. On a new build bought off-plan, no imputed income is charged while the property is still under construction.
If you let the property
This is where the non-EU position bites. Under Spain's Non-Resident Income Tax Act, owners resident outside the EU and the EEA are taxed at 24% on the gross rental income, with no deduction for community fees, repairs, insurance or agency commission. Only EU and EEA residents may deduct expenses.
On the Estepona average of €21 per square metre a month in August 2026, a 100 m² apartment let long-term brings in about €25,200 a year gross. A US-resident owner pays 24% of that gross figure, about €6,048, in Spanish tax before any cost has been met. That is not a reason to avoid letting, but it is a reason to model the investment on gross rather than net.
When you sell
The gain on a sale is taxed at 19% for all non-residents. The buyer withholds 3% of the price and pays it to the tax office on your account, and your own return settles the difference. The town hall also charges plusvalía on the increase in land value over the years you owned it.
The US side: FBAR, Form 8938 and the tax credit
The US taxes its citizens on their worldwide income, so Spanish property income appears on your US return as well as your Spanish one. Two reporting rules also apply, and one of them is widely misunderstood.
The reporting thresholds
The thresholds depend on where you live, which is a detail most summaries leave out.
| Report | Living in the US | Living abroad |
|---|---|---|
| FBAR, all foreign accounts | Over $10,000 at any time | Over $10,000 at any time |
| Form 8938, single | Over $50,000 at year end, or $75,000 at any time | Over $200,000 at year end, or $300,000 at any time |
| Form 8938, married filing jointly | Over $100,000 at year end, or $150,000 at any time | Over $400,000 at year end, or $600,000 at any time |
Because you will usually move the deposit and the purchase money through the Spanish account, it will very likely exceed $10,000 at some point in the year you buy, so plan on filing an FBAR for that year at least.
On double taxation, the principle is straightforward. Spain taxes the income and gains from Spanish property first. The US then taxes the same income as part of your worldwide income, and allows you to claim a foreign tax credit on Form 1116 for the Spanish income tax paid on it. Note the word income: the IRS makes clear that local property taxes such as IBI do not automatically qualify for the credit. The detail of how the credit works for your situation is a question for a US tax preparer who handles foreign property.
Owning from nine time zones away
The practical side of owning a Spanish home from the US is less about law than about logistics. Estepona is six hours ahead of New York and nine ahead of California, so the Spanish working day largely ends before yours begins. Most of what can go wrong is a letter nobody opened or a direct debit that failed.
Set up direct debits from your Spanish account for IBI, the refuse charge, the community fee and the utilities, so none of them depends on post reaching you abroad. Keep enough in the account to cover a year of those bills. Register an email address with the community administrator, who runs the owners' association, and read the minutes of the annual meeting, because that is where special levies for repairs are decided.
If you let the property, a local management company handles guests, cleaning and maintenance for a share of the income. If you do not, it is still worth having someone local with a key who can check the property after a storm or let in a plumber. On a new build, the first year matters most: finishing defects are the builder's responsibility for twelve months from the handover of the works, and someone needs to report them in writing inside that window.
Buying through a US LLC: why it is rarely worth it
Some American buyers are advised to hold Spanish property through a US limited liability company, as they might at home. For a single home here, that is usually more trouble than it is worth.
Spain does not treat a foreign company the way it treats a private owner. The defence zone rules extend to companies with majority non-EU ownership. A company owner cannot use a primary-residence exemption if you later move here. And Spain's Non-Resident Income Tax Act imposes a special annual levy of 3% of the cadastral value on property owned by entities resident in jurisdictions Spain treats as tax havens. Whether a particular US structure falls on the wrong side of any of these rules depends on its details, and that is exactly the problem: every structure needs checking, in two countries, by two sets of advisers.
Direct ownership in your own name, or jointly with your spouse, is simpler, cheaper to run and easier to sell. If you have a specific reason for a company, such as a larger portfolio, take advice from a Spanish and a US adviser together before you choose.
Can Americans buy property in Spain from the US? Yes, in a few clear steps
Start with one decision: holiday home or new home. If you are at the beginning: decide whether you are buying a holiday home or planning to live here, because that single decision determines your visa route, your tax position and even the kind of property that suits you. If you are moving, start with our guide to moving to Spain from the USA; if you are buying a second home, the rules above are what you need.
Once you have found a property: reserve, apply for your NIE, open a Spanish bank account and instruct an independent lawyer, all in the same week. Ask the lawyer to confirm the defence zone position along with the usual checks, set up your currency plan before the first payment is due, and note that the bank account will bring you into FBAR reporting for the year. And if you still wonder whether Americans can buy property in Spain on fair terms, the answer is that very few countries make it this straightforward. Our complete guide to buying property in Spain sets out the whole process, and the full list of developments covers the coast if you are still choosing where.
Frequently asked questions
Can Americans buy property in Spain?
Yes. US citizens can buy residential property in Spain on the same terms as Spanish nationals, with no quota, no minimum price and no need to live here. The one legal exception concerns a small number of designated defence zones, where a foreign buyer needs military authorisation.
Is there a 100% tax on Americans buying property in Spain?
No. A bill proposing a 100% tax on purchases by buyers resident outside the EU was admitted to Parliament in May 2025, but as of September 2026 it has not been passed and no such tax is in force. Purchases today are taxed under the normal rules.
Do I need a visa to buy property in Spain as an American?
No. The question "can Americans buy property in Spain without a visa" has a clear answer: buying requires no visa and no residence permit. Staying in Spain is a separate matter: without a visa, US citizens may spend up to 90 days in any 180-day period in the Schengen area, whether or not they own a home here.
Does buying property in Spain give an American residency?
No. Since the golden visa closed to new applications in April 2025, buying property no longer leads to residence on its own. Americans who want to live here use other visa routes, such as the non-lucrative or digital nomad visa.
Do I have to report Spanish property on FBAR or Form 8938?
Not the property itself. According to the IRS, foreign real estate held directly is not reportable on either form. Your Spanish bank account is: it counts towards the FBAR threshold of $10,000 and the Form 8938 thresholds.
How much tax does an American pay on rental income in Spain?
Owners resident in the US pay Spanish non-resident income tax of 24% on gross rental income, with no deductions for expenses. The Spanish tax paid can generally be claimed as a foreign tax credit against US tax on the same income.
What does it cost an American to buy property in Andalusia?
When asking "can Americans buy property in Spain at the same cost as locals", the answer is yes: on a resale, 7% transfer tax; on a new build, 10% VAT plus 1.2% stamp duty. Add notary, registry and legal fees on top. Nationality makes no difference to these rates.
Can an American get a mortgage in Spain?
Yes. Spanish banks lend to US citizens living in the US as non-residents, usually for a lower share of the price than residents receive, and with the same legal protections as any other borrower under Spain's 2019 Mortgage Credit Act.
Should an American buy Spanish property through an LLC?
For a single home, usually not. It adds cost and complexity on both sides of the Atlantic, can trigger extra authorisation rules in defence zones, and a 3% annual levy applies to entities resident in jurisdictions Spain lists as tax havens. Take advice before choosing a structure.
Do I need to be in Spain to buy property?
No. With a power of attorney granted to a Spanish lawyer, the whole purchase can be completed without you at the notary. Many buyers still come for the viewing and to sign the power of attorney in Spain.
Sources & official links
- BOE – Law 8/1975 on zones and installations of interest for national defence, Articles 18 to 21 (checked 21.09.2026)
- Congreso de los Diputados – BOCG Series B No. 229-1, Bill 122/000196 (30 May 2025) (checked 21.09.2026)
- IRS – Comparison of Form 8938 and FBAR requirements (checked 21.09.2026)
- IRS – Foreign tax credit (checked 21.09.2026)
- BOE – Non-Resident Income Tax Act (Royal Legislative Decree 5/2004), Articles 24, 25, 40 and 43 (checked 21.09.2026)
- Agencia Tributaria – Non-resident income tax on Spanish property (checked 20.09.2026)


