Beckham Law Spain: The 24% Tax Regime for People Who Move Here to Work
A new job, a sea view from the home office, and a tax rate that stays at 24% for six years. For many professionals, that combination is what turns the idea of moving to Spain into a plan. The Beckham law in Spain rewards people who come here to work, and on the Costa del Sol it comes with a lifestyle that is hard to match anywhere in Europe.
We moved to Estepona from Germany ourselves and went through the paperwork of settling here: the NIE, the residence registration, the padrón. Since 2019 we have worked with all the developers from Sotogrande to Marbella, and I look after every buyer personally. This guide explains the Beckham regime from the law itself, Article 93 of the Personal Income Tax Act, so you can plan your move with confidence, and it shows why Estepona is such a good place to enjoy the years it covers.
What the Beckham law in Spain is
The Beckham law is a special tax regime that lets people who move to Spain for work pay income tax largely as non-residents, at a flat 24% on their salary. It is written in Article 93 of the Personal Income Tax Act, and it takes its popular name from the footballer David Beckham, who moved to Real Madrid in 2003, around the time the first version of the regime was introduced.
The idea is simple. When you become tax resident in Spain because you have moved here, you can choose to be taxed under the rules of the non-resident income tax, with some special adjustments, while remaining a Spanish income tax payer. The choice applies for the tax year in which you become resident and the following five years: six tax years in total.
Since 2023, the regime has been open to far more people than before. The Startups Act extended it to remote workers, company directors, entrepreneurs and highly qualified professionals, and to their families. For anyone moving to Spain to work, it is one of the most attractive tax arrangements in Europe.
Who qualifies for the Beckham law in Spain
Two conditions decide it: you were not tax resident in Spain in the previous five years, and you move here for one of the reasons set out in the law. A third condition keeps the regime for individuals rather than for businesses operated through a Spanish branch.
The five-year rule is straightforward: you must not have been tax resident in Spain in any of the five tax years before the year of your move. Someone who has lived abroad and returns after six years or more can therefore qualify as well as someone who has never lived here.
The move must happen in the first year of the regime or the year before, and it must be for one of these reasons:
- An employment contract with an employer in Spain, or a posting ordered by your employer abroad with a letter of assignment.
- Remote work as an employee, carried out exclusively with computers and telecommunications, including employees on the digital nomad visa.
- Becoming a director of a company, with limits on your shareholding if the company mainly holds assets.
- An entrepreneurial activity recognised as such under the entrepreneurs' law, Law 14/2013.
- Highly qualified professional work for startups, or in training, research, development and innovation, making up more than 40% of your total income.
Finally, you must not earn income through a permanent establishment in Spain, except in the entrepreneur and highly qualified routes. Professional athletes under the special employment rules for sport are excluded; the regime is named after a footballer, but it is no longer open to them.
Remote workers and freelancers: which route fits you
If you work remotely as an employee, the law opens the Beckham regime to you directly; if you are a freelancer, the route runs through the entrepreneur or highly qualified professional categories. This distinction is the one to get right when you plan your move.
For employees, the law is explicit. The employment condition is met when the work is done remotely, exclusively with computers and telecommunications, even if your employer did not order the move. It names employees holding the international teleworking visa, the digital nomad visa, as meeting it. For a remote employee of a company abroad, the Beckham law and the digital nomad visa therefore fit together naturally. Our guide to the digital nomad visa explains the residence side.
For freelancers, the remote-work wording does not apply, because it refers to employment. A self-employed professional can qualify through the entrepreneur route, with an activity approved as entrepreneurial under Law 14/2013, or as a highly qualified professional serving startups or working in research, development and innovation, with that work making up more than 40% of their income. Both routes are real options with their own approval, and they are worth discussing with a Spanish tax adviser before you move rather than after.
The practical conclusion is positive: almost everyone who moves to Spain to work has a route into the regime. The question is simply which one, and that decides the documents you prepare.

Beckham law Spain for EU and non-EU nationals
The tax regime is the same for everyone; what differs is the residence side of the move. The Beckham law in Spain looks only at your tax residence and the reason for your move, not at your passport, but your passport decides how you arrive.
If you are an EU, EEA or Swiss citizen, you can move to Spain and work here freely. You register as a resident after three months, obtain your NIE, register with social security when you start work, and file form 149 within six months. No visa is needed, so the whole process is mainly a matter of timing and documents.
If you come from outside the EU, you first need a residence route that allows the work you will do. For a job with a Spanish employer, that is a work permit tied to the employment. For remote employees of companies abroad, it is the digital nomad visa, which the Beckham law names directly. For founders, the entrepreneur route under Law 14/2013 connects residence and tax, and for senior specialists there is the highly qualified professional permit. Our overview of the residence routes after the golden visa sets them side by side, and our guide on how to move to Spain covers the first steps after arrival.
Either way, the order is the same: residence route first, then social security registration, then form 149 within six months. Planning these three steps together is the single best thing you can do for a smooth start.
How income is taxed under the Beckham regime
Your salary is taxed at 24% up to €600,000, your Spanish savings at 19% to 30%, and most foreign income other than work stays outside the Spanish tax. That is the core of why the regime is so attractive.
| Income | How it is treated | Rate |
|---|---|---|
| Employment income, anywhere | Treated as Spanish | 24% up to €600,000, 47% above |
| Spanish dividends, interest, gains | Savings scale | 19% to 30% |
| Other Spanish income, such as rent | General scale | 24% up to €600,000 |
| Foreign dividends, interest, rents | Outside Spanish tax | – |
All your employment income counts as earned in Spain, even if your employer is abroad, and it is taxed at 24% up to €600,000. Above that, the rate is 47%. For an employee with a salary of €150,000, that means €36,000 in Spanish income tax for the year, a figure that is easy to plan with because it does not depend on the progressive scale.
Savings income from Spain, such as dividends, interest and capital gains, follows its own scale, in force since 2025: 19% up to €6,000, 21% up to €50,000, 23% up to €200,000, 27% up to €300,000 and 30% above. Other Spanish income, such as rent from a Spanish property, is taxed at the general rate of 24%. Spanish income is added up for the calendar year, without offsetting losses against gains.
Income from abroad that is not from work, such as foreign dividends, interest or rent from a property at home, is generally outside the Spanish tax under the regime. Whether and how it is taxed in the country it comes from is a matter for that country's rules, which is another reason to plan with an adviser who knows both sides.

When the Beckham law in Spain pays off most
The regime is most valuable for people with a good salary, savings or investments abroad, and a plan to stay several years. Three situations show where the Beckham law in Spain makes the biggest difference.
The first is a well-paid employee. Spain's ordinary income tax is progressive, with rates that rise with income and vary slightly by region, so the higher the salary, the more a flat 24% is worth. For someone on €150,000, the €36,000 of Spanish tax under the regime is a clear, fixed number that makes budgeting for a new life very simple.
The second is someone with income or assets abroad: investment portfolios, rental property at home, or a business interest in another country. Because most foreign income other than work stays outside the Spanish tax, and wealth tax applies only to Spanish assets, the Beckham law in Spain keeps these arrangements as they are for six years.
The third is a family moving together. With the extension to spouses and children, a household can settle in under one predictable set of rules. And for all three, the six years give time to find the right neighbourhood, choose a school, and buy a home without pressure. That calm is worth as much as the tax saving itself, because the first years in a new country are the ones that shape how at home you feel.
Bringing your family under the Beckham regime
Since 2023, your spouse and children can join the regime too, which makes a family move much easier to plan. The law extends it to your spouse, to children under 25, or of any age with a disability, and, if you are not married, to the other parent of your children.
Each family member must meet four conditions. They move to Spain with you, or later, as long as your first tax year under the regime has not ended. They become tax resident in Spain. They were not tax resident here in the previous five years and do not earn income through a Spanish permanent establishment. And the sum of their taxable bases in each year must be lower than yours.
In practice that means a family can move together and settle in under the same predictable tax rules. The regime continues for them in each year in which it also applies to you. For families, the move itself becomes easier too: Spanish state schools are free, the Costa del Sol has international schools in English and other languages, and children who start young pick up Spanish quickly.
Payroll, withholding and social security
Once the option is accepted, your salary is paid with 24% withholding, so the benefit shows up in your monthly pay rather than only at year end. How that works depends on who employs you.
With a Spanish employer, the payroll department applies the regime's withholding rate of 24% to your salary, and 47% to any amount above €600,000 paid by the same employer in the year. Give them the acknowledgement of your form 149 as soon as you have it. Your social security contributions continue as for any other employee, and they give you access to the Spanish public health system.
With an employer abroad, as a remote employee, the arrangements depend on the countries involved. The six-month deadline for form 149 runs from the start of your activity shown in your Spanish social security registration, or in the document that allows you to stay in your home country's social security system where that applies, so this document is the one to arrange first. A payroll provider or employer of record in Spain can take care of the Spanish side for companies that do not have their own entity here.
Each year you file form 151, the income tax return under the regime, with your Spanish income, the tax already withheld and any balance to pay or reclaim. A local tax adviser prepares it for a modest fee, and it becomes a routine part of the calendar, like the renewal of your home insurance.
Wealth tax and assets under the Beckham law
Under the regime, you pay wealth tax only on assets located in Spain, not on your worldwide assets. Article 93 states that a taxpayer who opts for the regime is subject to wealth tax under the "real obligation", the rules for assets in Spanish territory.
For people with savings, investments or property abroad, this is one of the most valuable parts of the regime. Assets outside Spain stay outside the Spanish wealth tax, and only Spanish assets, such as a home here or a Spanish bank account, count. Your adviser will check the thresholds and the rules that apply to your Spanish assets in the region where they are located.
If you plan to buy a home here during the regime, it is worth thinking about the structure of the purchase with your adviser at the start: in whose name, with what financing and how it fits the years after the regime ends. A New Build bought during the six years is a Spanish asset from the day of completion, and a well-planned purchase keeps everything simple.
How to apply for the Beckham law in Spain, step by step
The application is made with form 149 to the Spanish Tax Agency, within six months of the start of your activity in Spain. The deadline is firm, so the steps below belong in your moving plan from the start.
- Confirm your route with a Spanish tax adviser: employment, remote employment, director, entrepreneur or highly qualified professional.
- Get your Spanish tax number, the NIE or NIF, and make sure you are registered in the tax census.
- Start your activity and register with Spanish social security, or obtain the document that keeps you in your home country's system if that applies.
- Note the date of the start of activity shown in that registration: the six months run from here, not from your arrival.
- Prepare the evidence for your route: employment contract, letter of assignment, remote-work arrangement, director appointment or approval of your activity.
- File form 149 with the Tax Agency within the six months and keep the acknowledgement.
- Ask your employer to apply the 24% withholding rate once the option is accepted.
- File form 151 each year as your income tax return under the regime.
Form 149 is also used later to communicate a waiver, an exclusion or the end of your stay in Spain. The Tax Agency's page for form 149 sets out the procedure. Your NIE number is the first practical step, and our guide explains how to get it.
Six years of Beckham, and what comes after
The regime covers the year you become resident and the next five, and a little planning makes the transition afterwards smooth. Six tax years is a long time to settle in, build a life and, for many, buy a home.
- Year of arrival Tax residence begins; form 149 within six months of starting your activity.
- Years 2 to 6 The regime continues while the conditions are met; form 151 each year.
- Year 6 The right time to plan with your adviser for the ordinary rules that follow.
- From year 7 Ordinary Spanish income tax as a resident, on worldwide income, with double taxation treaties.
After the regime, you are taxed like any other Spanish resident, on worldwide income and under the progressive scale, with double taxation treaties preventing tax twice. As a resident you also join the ordinary wealth tax rules, where in Andalusia a 100% regional reduction applies to residents. Planning the last year of the regime with your adviser, for example the timing of bonuses, the sale of investments or the structure of your assets, lets you move from one system to the other without surprises.
The residence side runs in parallel. If you came on the digital nomad visa, your permit is renewed for two years at a time, and after five years of legal residence you can apply for long-term residence. EU citizens simply stay registered as residents.
A checklist before you opt in
The Beckham regime is attractive for most people who move to Spain to work, and a short checklist confirms it for your own situation. Go through these points with your adviser before you file form 149:
- You were not tax resident in Spain in the five previous tax years
- Your move fits one of the routes in the law, with documents to show it
- The six-month deadline from the start of your activity is in your calendar
- Your income mix suits the regime: salary, savings, foreign income
- Your family members meet the conditions if they are to join
- Your assets abroad and in Spain have been reviewed
- Your home country's tax rules on leaving are clear
- You have a plan for the years after the regime
For most employees with a good salary, the answer is a clear yes. For people with large foreign income or complex structures, the regime can be even more attractive, and the one meeting with an adviser pays for itself many times over.
Your first months in Spain under the Beckham regime
The first months are about a few appointments, and then the regime runs quietly in the background while you enjoy your new life. The order below keeps everything in line with the deadlines.
Register on the padrón at the town hall with your rental contract, which confirms your address. Collect your NIE and your residence document: the EU registration certificate, or the TIE if you came on a visa. Open a Spanish bank account for your salary, rent and direct debits. Register with social security when your activity starts, and write the date in your calendar together with the date six months later.
Then file form 149, tell your payroll, and turn to the things that make a new life: the school for the children, the gym, a Spanish course, the first friends. Under the Beckham law in Spain, your tax position is settled for six years, which leaves your attention free for everything else. Many of the practical steps, from healthcare to driving licences, are covered in our guide to moving to Spain from the UK and our guide to moving to Spain from the USA.
Why Estepona is a great place to live under the Beckham law
If you move to Spain to work, Estepona gives you a real town, the sea, fast connections and a better home for your budget. It is the kind of place where a working life and a good life fit together.
Estepona has almost 80,000 residents, a restored old town full of flowers, 21 kilometres of coastline and a long seafront promenade, and it lives all year. According to the town hall, it has repaid its inherited debt, has funded its own hospital, has almost completed a coastal path of more than 21 kilometres and is investing around €27 million in its 2026 budget. Málaga airport is 84 kilometres away, with flights across Europe, and Gibraltar 45, so trips to clients and head offices are easy.
For a remote employee, the town works perfectly: cafés for a change of scene, a gym and a padel court after work, the beach for a swim at lunchtime, and a time zone shared with most of continental Europe. On our own analysis, long-term rents in Estepona averaged €21 per square metre a month in August 2026, and new developments were asking €5,145 per square metre on our survey of 18 September 2026, against €7,491 in our Marbella market area. For the same budget, you get more space in Estepona, and a proper home office with a view.
Buying a home during the Beckham years: why New Builds fit
Six predictable tax years are a very good window to settle in and buy, and a New Build fits the rhythm of a working move. Buying is open to everyone, resident or not, so you can buy at the time that suits you.
Off-plan, the construction months run in parallel with your first period here: you start work, rent in the area you have chosen and learn the town while your home is being built. When the keys arrive, you move into a home built to current standards, with modern insulation, air conditioning and fast connections, and a room designed as a home office. Payments during construction are protected by a bank guarantee or insurance in your name once the building licence is granted, and the law provides warranties of up to ten years after handover.
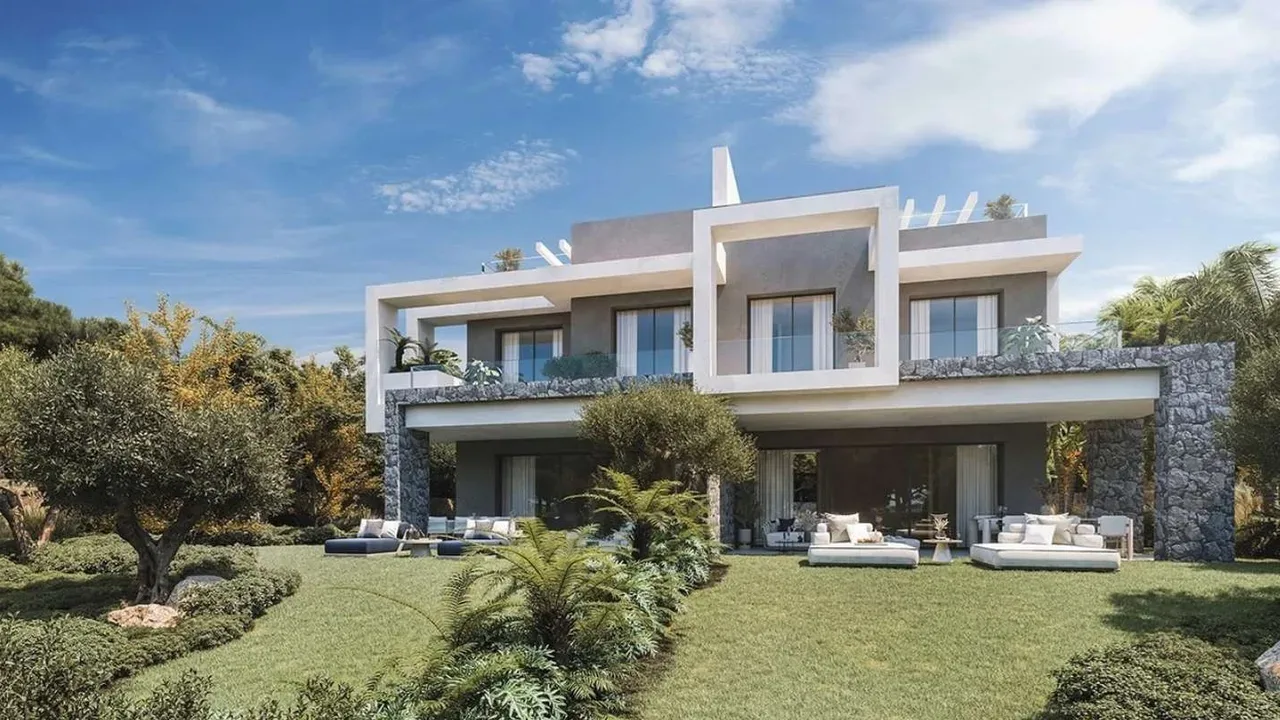
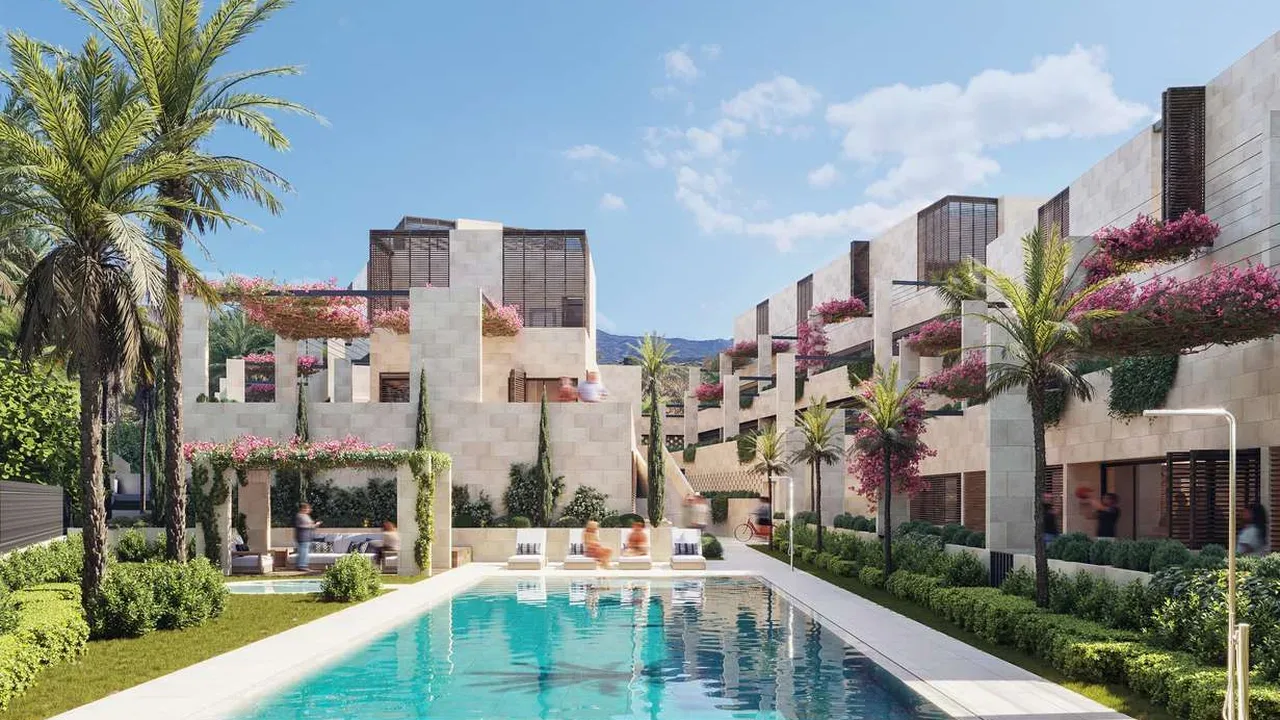
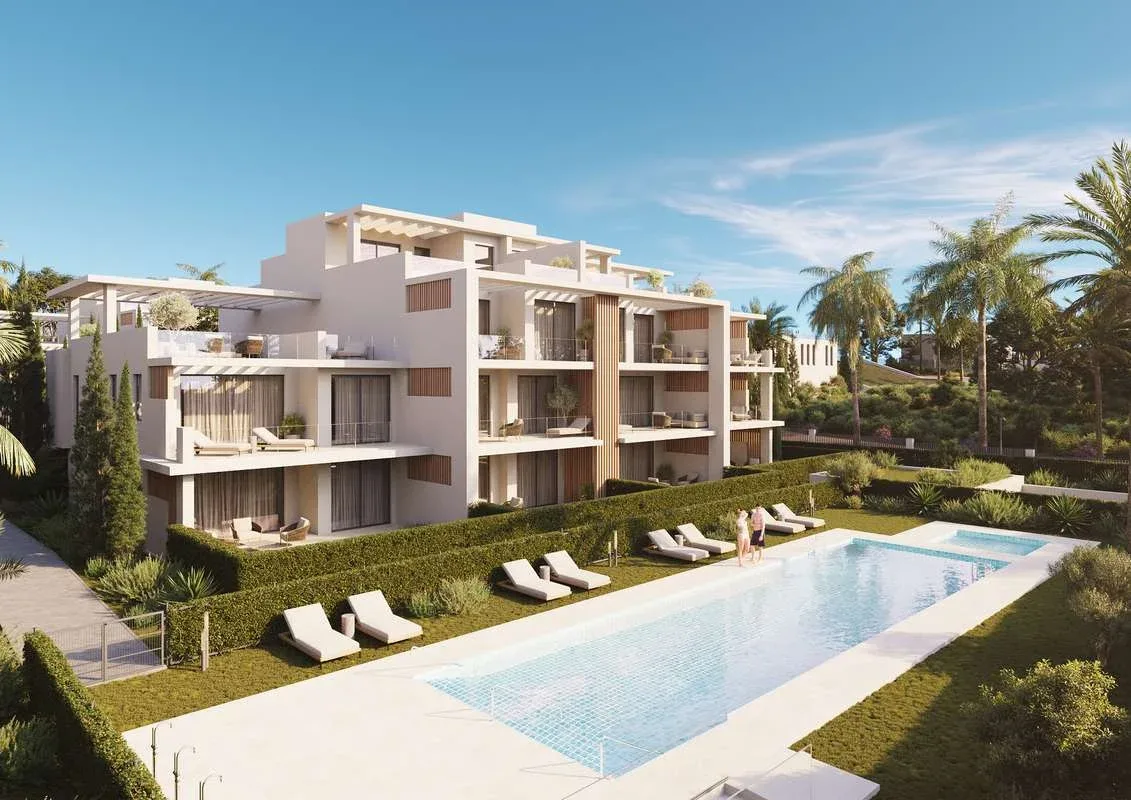
In Estepona, New Builds cost little more than second-hand homes, only 2.9% above the Resale index in September 2026. Our complete guide to buying property in Spain covers the purchase, our guide to buying off-plan in Spain explains the protections, and our guide to Spanish mortgages explains financing. The new developments in Estepona show the choice available today.
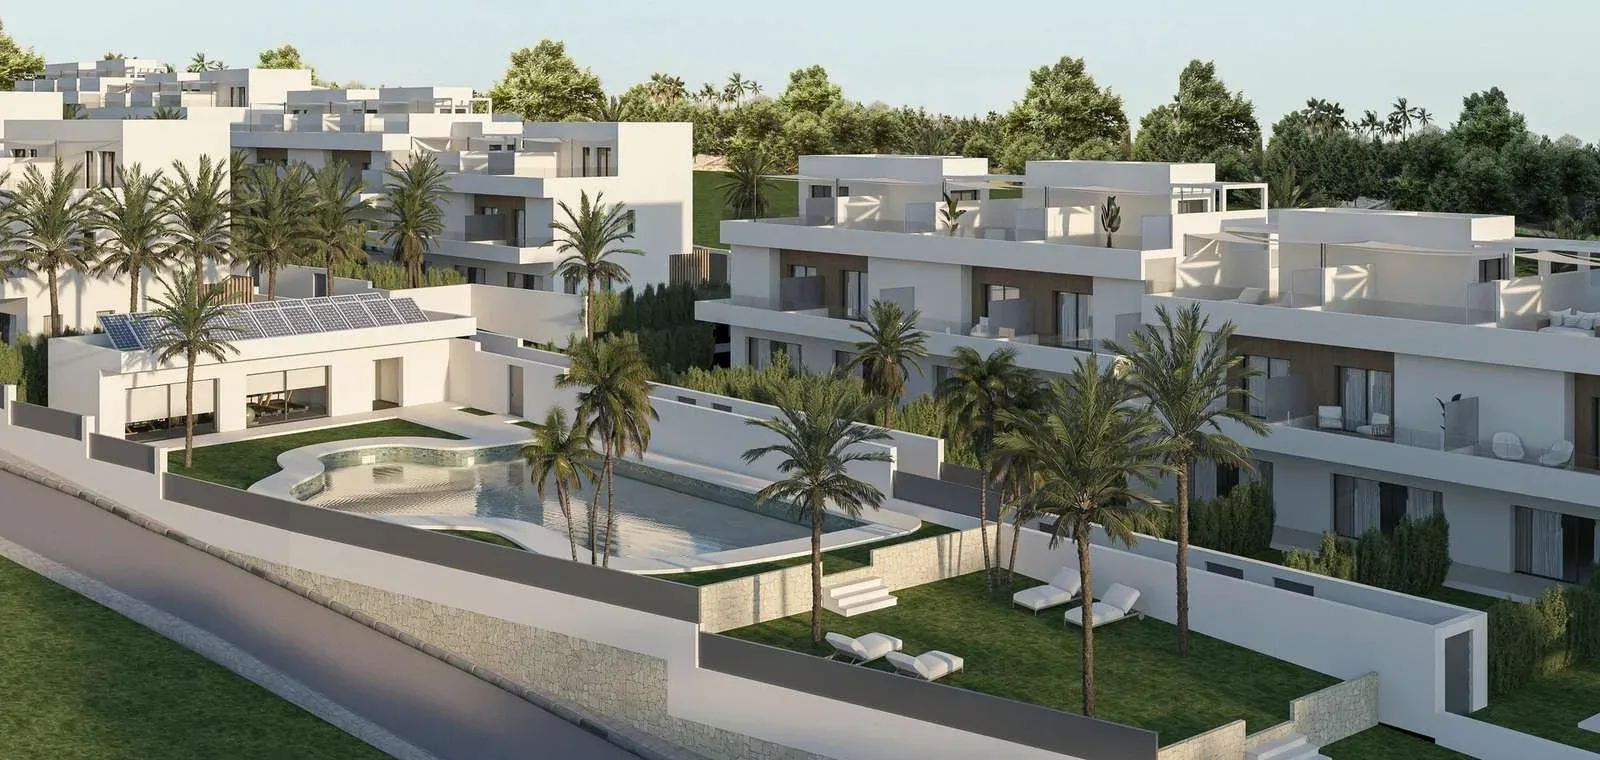
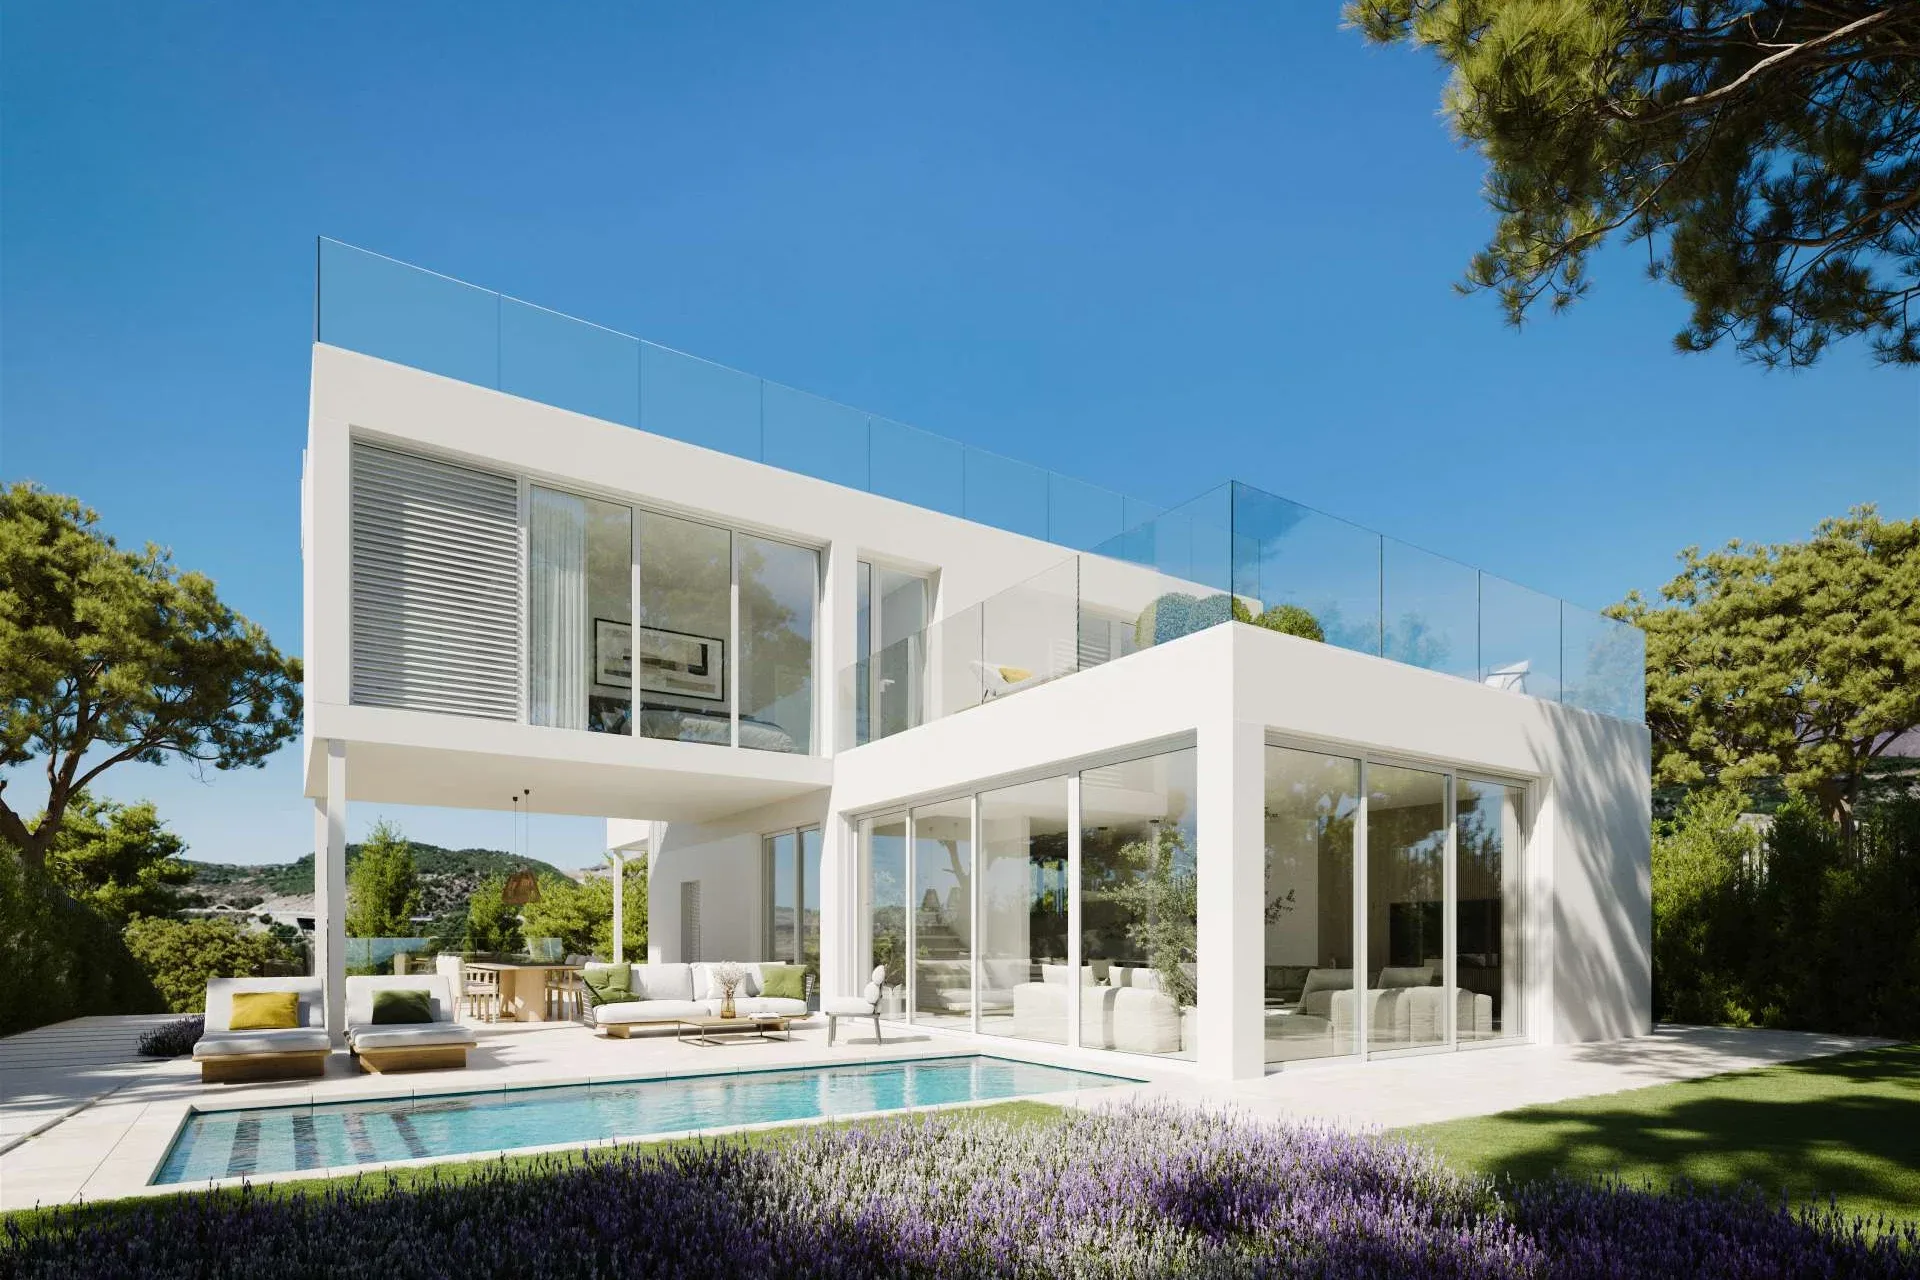
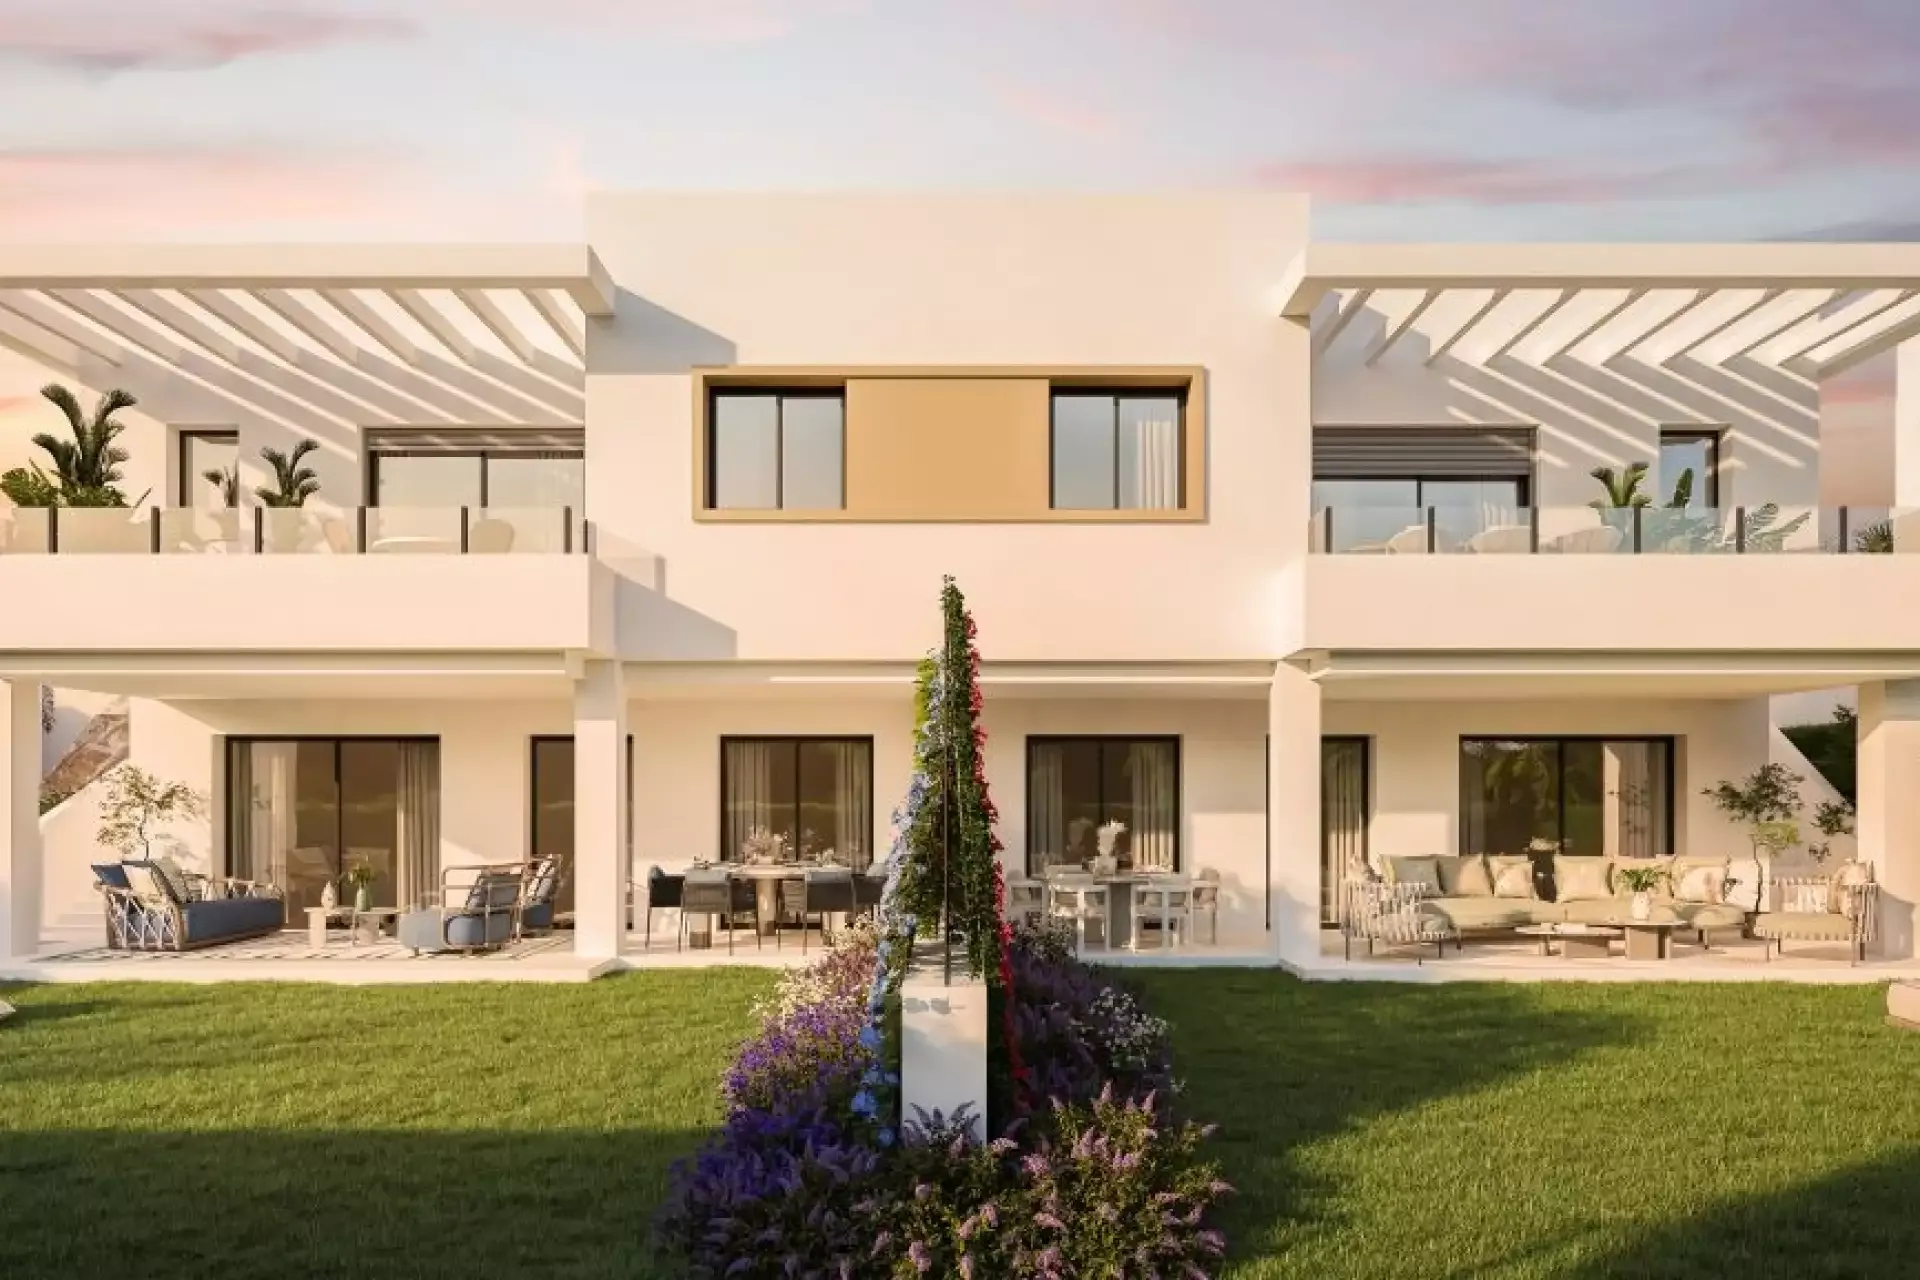
New developments in Estepona
Beckham law Spain: route first, then the deadline, then the town
Start with your route, then the deadline, then the town. Confirm with a Spanish tax adviser which route in Article 93 applies to you and what evidence you need. Put the six-month deadline in your calendar the moment your activity starts, get your tax number early, and file form 149 in good time.
Then plan the part you will enjoy most: where you will live. Come to Estepona for a few days, see the old town, the promenade and the new developments, and imagine your working week here, with a swim before lunch and dinner on the terrace. The Beckham law in Spain makes the numbers work; the Costa del Sol makes the life worth it.
Frequently asked questions
What is the Beckham law in Spain?
The Beckham law in Spain is the popular name for the special tax regime in Article 93 of the Personal Income Tax Act. People who become tax resident in Spain because they move here for work can choose to be taxed under non-resident rules, with employment income taxed at 24% up to €600,000, for the year of arrival and the following five.
Who qualifies for the Beckham law?
You must not have been tax resident in Spain in the five previous years, and you must move because of an employment contract, remote work as an employee, becoming a company director, an approved entrepreneurial activity or work as a highly qualified professional for startups or in research and innovation.
Can freelancers use the Beckham law?
Not through ordinary self-employment. The remote-work route in the law is for employees. Freelancers can qualify through the entrepreneur route, with an activity approved as entrepreneurial, or as highly qualified professionals serving startups or doing research and innovation.
How long does the Beckham law last?
For the tax year in which you become resident and the following five, six tax years in total, as long as the conditions continue to be met.
How do I apply for the Beckham law in Spain?
With form 149 to the Spanish Tax Agency, within six months of the start of your activity as shown in your Spanish social security registration. You need a Spanish tax number first. Each year you then file form 151.
Is foreign income taxed under the Beckham law?
All employment income counts as Spanish and is taxed at 24% up to €600,000. Most other income is taxed in Spain only if it comes from Spain, so under the Beckham law in Spain foreign dividends, interest and rents generally fall outside the Spanish tax.
How are savings taxed under the regime?
Spanish dividends, interest and capital gains are taxed at 19% up to €6,000, 21% up to €50,000, 23% up to €200,000, 27% up to €300,000 and 30% above that, the scale in force since 2025.
Can my family use the Beckham law too?
Yes. Your spouse and children under 25, or of any age with a disability, can opt in if they move with you or later in your first year of the regime, become tax resident, and their combined taxable base stays below yours.
What about wealth tax?
Under the Beckham regime you are taxed for wealth tax only on assets located in Spain, not on your worldwide assets.
Can I buy a home in Spain under the Beckham law?
Yes. Buying is open to everyone, and the six years of the regime are a comfortable window to settle in and buy. Rent and gains from Spanish property are Spanish income and are taxed under the regime's rules.
Sources & official links
- BOE – Personal Income Tax Act 35/2006, Article 93 (special regime for inbound workers) (checked 22.09.2026)
- Agencia Tributaria – Form 149, option for the special regime (checked 22.09.2026)
- Agencia Tributaria – Form 151, tax return under the special regime (checked 22.09.2026)
- Agencia Tributaria – Special regime for workers moving to Spain (checked 22.09.2026)
- BOE – Law 14/2013, international teleworking and entrepreneurial activity (checked 21.09.2026)
- Ayuntamiento de Estepona – 2026 budget (checked 21.09.2026)